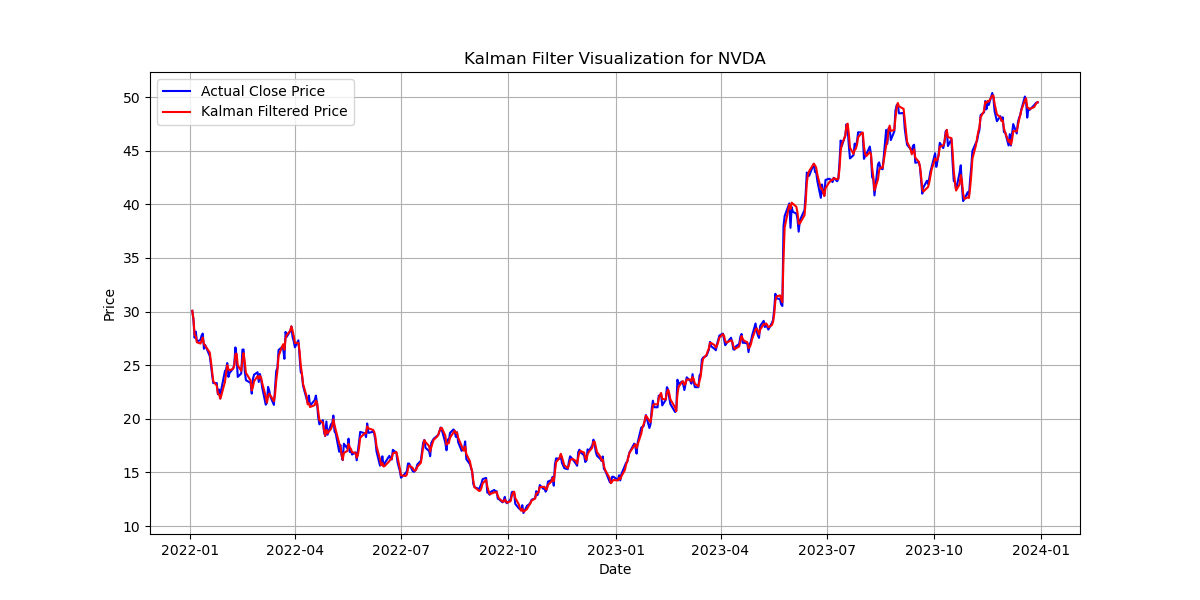
This project applies a Kalman filter to historical stock market data to estimate the true underlying price signal beneath the noise of daily market fluctuations. Implemented from scratch in Python using NumPy, the filter models the stock price and its trend as a hidden state, continuously refining its estimate as new observations arrive.
The project demonstrates how a classical signal processing algorithm can be applied to financial time series — balancing model uncertainty and measurement noise through two tunable parameters, Q and R. Built with yfinance for data retrieval and Matplotlib for visualization.
Example (NVIDIA):